On July 24, 2026, FinCEN issued a formal Alert directing financial institutions to detect, prevent, and report suspicious activity connected to fraud schemes targeting federal student aid programs. Ghost students, straw students, and money-mule payroll structures are the primary typologies, and financial institutions are the front line of defense.
FinCEN issued a formal Alert on July 24, 2026 directing financial institutions to detect and report suspicious activity connected to Federal student aid fraud
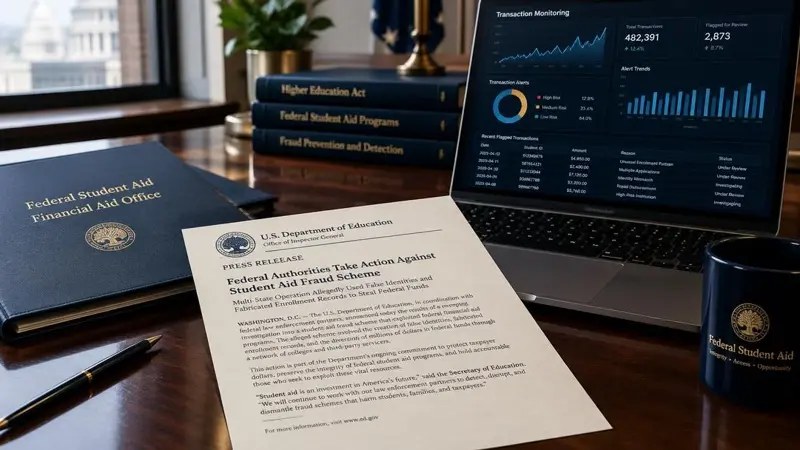
On July 24, 2026, the U.S. Department of the Treasury's Financial Crimes Enforcement Network issued a formal Alert urging financial institutions to detect, prevent, and report suspicious activity connected to fraud schemes targeting student aid programs administered by the Federal government. The announcement, made alongside Secretary of the Treasury Scott Bessent's statement that "every dollar stolen from Federal student aid is a dollar taken from taxpayers and deserving students," is part of Treasury's broader effort, led by President Trump and Vice President Vance, to eliminate government benefits fraud. It is a direct compliance obligation, not background reading, and financial institutions should treat it accordingly.
Two primary scheme types are identified: ghost student schemes using stolen PII and synthetic identities, and straw student networks using complicit real individuals for a fee
The scale of the problem is significant. Fraud rings use stolen and fraudulent identities, as well as other tactics, to enroll in educational institutions and unlawfully acquire funds from Federal student aid programs. The schemes not only result in losses to Federal student aid programs, but in some cases, real students face difficulties enrolling in classes because of the number of fraudulently enrolled "students" crowding waitlists and consuming financial aid allocations meant for legitimate applicants. The harm flows in two directions: taxpayer funds are diverted, and genuine students are displaced.
Student aid refunds disbursed via ACH with transaction references including "REFUND" and the institution's name or abbreviation are the primary transaction pattern to monitor
FinCEN identifies two primary fraud methodologies that financial institutions should understand and monitor for. The first is the "ghost student" scheme, built on identity theft. To create ghost students, fraudsters may illegally obtain Personally Identifiable Information to impersonate an identity theft victim and pose as a legitimate student. Fraudsters may also use artificial intelligence or other tools to overcome identity verification by generating fraudulent documents that combine stolen PII with fabricated details, commonly referred to as synthetic identities. Victims whose identities are leveraged as part of ghost student schemes, including minors, are unaware that fraudsters are receiving Federal student aid using their PII, which can result in tax consequences and benefit denials for the actual identity holder.
Post-refund activity is the clearest signal: rapid outbound transfers, structured movements, and remittances to unrelated accounts following educational refund deposits indicate money mule activity
The second methodology involves "straw students", complicit individuals who, for a fee, provide their PII to fraudsters, who then enroll them at educational institutions and collect financial aid refunds issued in their names. Fraudsters may organize sophisticated networks of individual straw students to obtain Federal student aid at scale. Corrupt staff at educational institutions can also act as insiders for fraud schemes, taking advantage of their positions to defraud Federal student aid programs by recruiting straw students and manipulating their educational records.
Synthetic identity fraud, combining real SSNs with fabricated biographical details, challenges standard CIP procedures and may require additional cross-referencing beyond SSN verification
For financial institutions, the most actionable guidance in the Alert concerns how student aid refund payments flow through the financial system, and what that flow looks like when it involves fraud. Financial institutions may be able to identify student aid refund payments either through deposits made directly by educational institutions or by contracted intermediaries. According to Bank Secrecy Act data, payments made by an intermediary typically occur via Automated Clearing House transfers, and the associated transaction references may include the term "refund" and the educational institution's name or abbreviation, for example, "Local Community College Refund" or "LCC REFUND." In some cases, the stated recipient may also be listed in the transaction reference, such as "LCC REFUND John Doe."
Corrupt insiders at educational institutions mean historical disbursement patterns from a known institution do not guarantee legitimacy of all future disbursements
Once fraudsters obtain student aid refunds, the laundering begins. After illicitly obtaining student aid refunds, fraudsters may launder student aid funds including through money mules, shell companies, and fraudulent accounts. The money mule layer is particularly important for financial institutions to understand: accounts receiving these refund payments may then immediately transfer funds to unrelated accounts, move funds in structured amounts to avoid reporting thresholds, or send rapid remittances to accounts associated with known fraud typologies. The velocity and direction of activity immediately following a refund deposit is often the clearest signal available.
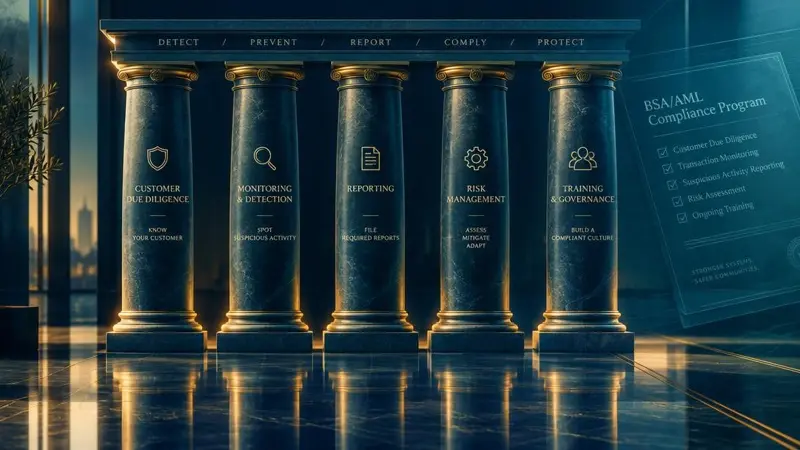
Financial institutions should update monitoring rules, brief SAR investigators on the typologies, review CIP procedures for synthetic identity indicators, and document their compliance response
What transaction monitoring indicators should compliance teams be watching for? Several patterns emerge from the Alert's description of scheme mechanics. First, student aid refund deposits arriving via ACH from educational institution intermediaries should be reviewed for consistency with the account holder's known profile, a recently opened account with no prior deposit history that suddenly receives multiple "LCC REFUND" transfers warrants scrutiny. Second, accounts that receive these deposits and immediately transfer funds outward, particularly to multiple different recipients in rapid succession, exhibit the velocity pattern characteristic of money mule activity. Third, accounts held by individuals who receive "refund" payments from institutions they have no other documented relationship with present a profile inconsistency that should trigger enhanced review.
SAR narratives for this typology should reference "student aid fraud" or "Federal student aid refund fraud" and include details about the educational institution, payment intermediary, and downstream recipients
The Alert also has direct implications for account opening and customer identification. Ghost student schemes require fraudsters to open or access financial accounts to receive the disbursed funds. Accounts opened with synthetic or stolen identities, high-quality fabricated documents combining real PII with fabricated photos or biographical details, are a growing challenge for CIP procedures. Financial institutions should review whether their identity verification procedures are adequate for detecting synthetic identity fraud, which specifically combines genuine elements (real SSNs, real addresses) with fabricated elements (photos, signatures, or names not associated with the actual identity holder). Relying solely on SSN verification without cross-referencing against behavioral signals, device data, or other independent verification sources creates meaningful exposure.
The straw student network has a different profile than the ghost student scheme, and the financial patterns differ as well. Straw students are real individuals who voluntarily provide their PII and receive refund deposits into their own accounts. The distinguishing characteristic is what happens after the deposit: the straw student transfers the funds to the fraudster, keeping a fee. From a monitoring perspective, accounts belonging to straw students may show a pattern of receiving intermittent large deposits from educational institutions, followed immediately by outbound transfers that consume nearly the entire deposit balance. Multiple individuals at the same address receiving similar "refund" deposits from the same educational institution is another pattern consistent with organized straw student recruitment.
The insider element, corrupt staff at educational institutions, creates a more complex compliance challenge because it means that some of the disbursements triggering suspicious activity may originate from institutions with legitimate disbursement histories. A financial institution that has received clean educational refund payments for years cannot assume that all future payments from the same institutional source are legitimate. Unexplained increases in disbursement volume, disbursements to accounts with no prior connection to the institution, or disbursements to accounts whose holders show no evidence of educational enrollment activity are all indicators worth flagging.
FinCEN's Alert is part of Treasury's broader commitment to eliminating government benefits fraud, framed as an objective of Executive Order 14249, Protecting America's Bank Account Against Fraud, Waste, and Abuse. The political context matters for financial institutions because it signals that this is an active enforcement priority, not a guidance document that will sit unmonitored. Institutions that receive regulatory examinations in the coming cycle should expect questions about their response to this Alert, including whether they updated monitoring parameters, trained relevant staff, and documented the compliance steps they took in response.
The practical compliance response for financial institutions has several components. First, review your current transaction monitoring rules to determine whether any existing rules are calibrated to detect the patterns described in the Alert: ACH refund deposits from educational institutions, rapid outbound transfers following such deposits, and account opening activity consistent with synthetic identity fraud. If not, consider whether rule additions or threshold adjustments are warranted. Second, brief your SAR investigators on the scheme typologies. Ghost student and straw student schemes do not fit neatly into the most common SAR narrative frameworks, investigators who have not seen these typologies may not recognize them in account activity. Third, review your account opening procedures for synthetic identity indicators, which are increasingly sophisticated and may evade standard SSN-based verification without additional cross-referencing.
Fourth, consider whether any customer segments in your portfolio present elevated exposure. Institutions serving large student populations, those in geographic markets with significant post-secondary educational infrastructure, and those that process ACH disbursements for educational institutions should treat this Alert with particular attention. The Alert is not limited to these segments, refund laundering can flow through any financial institution, but these profiles represent the highest concentration of exposure. Fifth, document your compliance response. Regulators expect to see that financial institutions read and acted on FinCEN guidance. A documented review of existing monitoring rules, a training record showing that investigators were briefed, and a policy update noting that the Alert was reviewed and incorporated into monitoring protocols creates the evidence trail that demonstrates an active compliance program.
SAR filing connected to activity matching this Alert's typologies should describe the specific indicators that triggered suspicion, the pattern of refund deposits, the velocity of outbound transfers, the account opening characteristics, in enough detail that law enforcement can evaluate the filing. FinCEN has not issued a specific SAR key term for this Alert at the time of publication, but filers should include references to "student aid fraud" or "Federal student aid refund fraud" in the SAR narrative, along with all available information about the educational institution referenced in the transaction, the payment intermediary involved, and the downstream accounts or recipients of transferred funds.
The student aid fraud Alert is a reminder that financial crime threat vectors are not limited to money services businesses, banks serving high-risk customer segments, or institutions in high-risk geographic markets. Government benefits fraud, including student aid fraud, flows through mainstream financial infrastructure, ordinary checking accounts, standard ACH disbursement channels, and routine consumer banking relationships. Financial institutions of all types and sizes should review this Alert and assess their monitoring and detection capabilities against the typologies it describes. The cost of detection failure in a government-priority enforcement area is considerably higher than the cost of a calibrated monitoring response.